Showing posts with label home buyers. Show all posts

Tuesday, September 15, 2015

Construction, Retail Sales Higher

The Mortgage Corner

The strength of the economy right now is in the housing and construction sectors, again areas insulated from global factors, such as China’s slowdown. Construction spending, next to vehicle sales, is perhaps the week's best surprise, rising 0.7 percent for a second straight month, and 13.7 percent annually. Why? Rents are rising fast, which means many householders will start thinking about whether buying with today’s ultra-low mortgage rates as the better alternative.

image

Graph: Econoday

The Econoday graph shows the slope has steepened nicely in the spring and summer. The latest gain is centered in the most important component of all, single-family homes where construction spending rose 2.1 percent in the month for a year-on-year gain of 15.8 percent. Multi-family homes slowed in the month but the year-on-year rate, reflecting demand tied to high rents, is still outstanding at 21.2 percent.

image

Graph: Econoday

And auto sales are up a surprising 1.5 percent to a 17.8 million annual rate, with 14.1 million sales of domestic-made vehicles. The gain points to another strong month for retail sales in what would underscore the insulated strength of the domestic economy. It was outsized strength in the auto sector that supported the factory sector in June and July, though August's sales gain was centered in foreign-made vehicles. Still, sales of domestic-made cars and light trucks, which make up 80 percent of all sales, are at very strong levels.

In fact, retail sales just in this morning show a 2.2 percent annual gain, with strong sales in auto and food service. It could ave been above 3 percent if gas prices hadn’t fallen, but then would consumers be buying as much if gas prices were higher? This should mean Q3 GDP growth will again exceed 3 percent, following a revised Q2 reading of 3.7 percent by the BEA.

image

Graph: Calculated Risk

Will more renters be buying homes this year? The best way to compare rents to housing prices is the price-to-rent ratio. It is leveling off, which means rents are rising as fast as housing prices—some 5 percent of late. Combine that with conforming 30-year fixed mortgage rates of 3.75 percent, and we will have more renters looking to buy a home this year, at least. And the tax advantages of owning vs. renting really mean it’s more advantageous to buy over the longer term, rather than give the tax advantages to a landlord.

Harlan Green © 2015

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Tuesday, August 25, 2015

Record Post-Recession Home Sales, Construction, Case-Shiller Prices in July

The Mortgage Corner

With all the bad news coming from the stock market, it’s good to know that this hasn’t affected the housing market. In fact, it’s pushing interest rates lower, so that a conforming 30-year fixed mortgage rate has dropped to 3.50 percent in California. And that will continue to boost home sales (and prices, of course). That’s why Case-Shiller shows two cities already above their bubble highs, and the Conference Board’s Index of Leading Economic Indicators (LEI) shows continued strong growth ahead.

Total existing-home sales, which are completed transactions that include single-family homes, townhomes, condominiums and co-ops, increased a whopping 2 percent to a seasonally adjusted annual rate of 5.59 million in July from a downwardly revised 5.48 million in June. Sales in July remained at the highest pace since February 2007 (5.79 million), have now increased year-over-year for ten consecutive months and are 10.3 percent above a year ago.

image

Graph: Econoday

Lawrence Yun, NAR chief economist, says the increase in sales in July solidifies what has been an impressive growth in activity during this year's peak buying season. "The creation of jobs added at a steady clip and the prospect of higher mortgage rates and home prices down the road is encouraging more households to buy now," he said. "As a result, current homeowners are using their increasing housing equity towards the downpayment on their next purchase."

And demand is well ahead of thin supply, at 4.8 months at the current sales rate vs 4.9 and 5.1 in the two prior months and 5.6 months in July last year. Sales are up 10.3 percent year-on-year, well ahead of the median price which, at $234,000, is up 5.6 percent.

The S&P/Case-Shiller U.S. National Home Price Index recorded a higher year-over-year gain with a 4.5 percent annual increase in June 2015 versus a 4.4 percent increase in May 2015. The smaller 10-City Composite had marginally lower year-over-year gains, with an increase of 4.6 percent year-over-year. Denver and Dallas are the two cities now above their 2007 bubble highs, while Denver (+10.2%), San Francisco (+9.5%) and Dallas (+8.2%) had the biggest year over year increases.

image

Graph: Calculated Risk

This mismatch of supply vs. demand means even higher existing-home prices ahead. Especially since housing construction is just beginning to play catch up after years of low growth—no coincidence, given the rising demand for housing of any kind—rental as well as for prospective homeowners. Led by a strong jump in single-family production, nationwide housing starts inched up 0.2 percent to a seasonally adjusted annual rate of 1.206 million units in July, according to newly released data from the U.S. Department of Housing and Urban Development and the Commerce Department. This is the highest level since October 2007.

It’s also why the Conference Board’s Index of Leading Economic Indicators (LEI) continues to show moderate growth for the next 6 months, and is up 1.7 points from January to July. “The U.S. LEI fell slightly in July, after four months of strong gains. Despite a sharp drop in housing permits, the U.S. LEI is still pointing to moderate economic growth through the remainder of the year,” said Ataman Ozyildirim, Director of Business Cycles and Growth Research at The Conference Board.

Swings in housing permits have been distorting recent LEI readings including for July. Permits, which fell 16 percent in Tuesday's housing starts report, more than offset what are a run of mostly neutral readings among other components. Given the uncertainties of measuring housing data (readings with plus or minus 11 percent variations are common) the index could have added another 0.54 points to the July indicator, instead of subtracting that amount, for a much stronger reading.

The strongest component is the rate spread which reflects the Fed's ongoing accommodative policy. Also pointing to strength are initial jobless claims, which are at rock bottom lows, and the report's credit index which points to a rise ahead for lending.

So what’s happening in China and the so-called emerging markets (including the Petro states, and Russia) will help to keep interest rates low, housing strong, and maybe the Fed from raising their short-term rates for some time to come.

Harlan Green © 2015

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Wednesday, August 19, 2015

Higher Birth Rates Are Here

The Mortgage Corner

The mellennial generation, now aged 18 to 36 years, are beginning to drive higher birth rates. And that means more households being formed, which will ultimately create a higher demand for housing. Actually, a 4 million birth rate was breached in 2007, and births then declined due to the Great Recession. But the millennials are back above the 4 million birth rate again.

And housing construction is surging—no coincidence, given the rising demand for housing of any kind—rental as well as for prospective homeowners. Led by a strong jump in single-family production, nationwide housing starts inched up 0.2 percent to a seasonally adjusted annual rate of 1.206 million units in July, according to newly released data from the U.S. Department of Housing and Urban Development and the Commerce Department. This is the highest level since October 2007.

“This month’s drop in the more volatile multifamily side is a return to trend after an unusually high June,” said NAHB Chief Economist David Crowe. “While multifamily production has fully recovered from the downturn, single-family starts are improving at a slow and sometimes intermittent rate as consumer confidence gradually rebounds. Continued job and economic growth will keep single-family housing moving forward.” 

Births had declined for five consecutive years prior to increasing in 2013. They are about 7.7 percent below the peak in 2007 (births in 2007 were at the all-time high - even higher than during the "baby boom"). “I suspect certain segments of the population were under stress before the recession started,” says Calculated Risk’s Bill McBride, “- like construction workers - and even more families were in distress in 2008 through 2012. And this led to fewer babies.”

image

Graph: Calculated Risk

The above historical graph dates back to 1909, and the largest dip was before and during the Great Depression. It hit bottom in 1933, before beginning to rise again until it hit the baby boomer bulge of the 1950s and 60s.

This has to be the main reason home builder sentiment is at a 10-year high. The new home sector is increasingly a central source of strength for the economy and builders are increasingly optimistic, says the NAHB. The housing market index rose 1 point to a very strong 61 in August with the future sales component leading the way at 70. Current sales are at 66 with traffic continuing to lag but less so, at 45 for a 2 point gain in the month.

“Today’s report is consistent with our forecast for a gradual strengthening of the single-family housing sector in 2015,” said NAHB Chief Economist David Crowe. “Job and economic gains should keep the market moving forward at a modest pace throughout the rest of the year.”

Single-family starts rose 12.8 percent to a seasonally adjusted annual rate of 782,000 units after an upwardly revised June reading while multifamily production fell 17 percent to 424,000 units. And rising single family starts is another sure sign that more families and households are being formed.

What age group is having the most births? It is women in their 30s. The preliminary birth rate for women aged 30–34 in 2014 was 100.8 births per 1,000 women, up 3 percent from the rate in 2013 (98.0). The rate for this group has increased steadily since 2011. The number of births to women in their early 30s also increased in 2014, by 4 percent.

The rate for women aged 35–39 was 50.9 births per 1,000 women, up 3 percent from 2013 (49.3). The rate for this group has increased steadily since 2010. The number of births to women in their late 30s increased 5 percent in 2014.

Need we say more about the rising birth rate? All signs point to another upsurge in new household formation, needless to say, the main driver of real estate sales and the concomitant sectors that aid and drive RE—jobs in construction, insurance, professional fields, and banking, for starters.

Could it be that the real estate industry will drive 3 percent plus GDP growth for the rest of 2015, even if interest rates rise slightly? Rates are still at record lows with the conforming 30-year fixed rate at 3.625 percent for 1 origination point, and purchase mortgage applications still up 19 percent year over year, reports the Mortgage Bankers Association.

Harlan Green © 2015

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Thursday, July 23, 2015

Will Fannie and Freddie’s Investors Finally Succeed?

Financial FAQs

It is welcome news for Fannie Mae and Freddie Mac investors that Judge Margaret Sweeney in the Federal Claims Court in Washington Tuesday granted a motion that will force the U.S. Treasury to release all discovery document materials in its possession that pertain to the decision to take Fannie Mae and Freddie Mac into conservatorship.

Why? Because the White House, US Treasury, and Federal Housing Finance Authority have been stonewalling discovery requests by investors who want to know exactly why the GSEs were put into conservatorship in the first place.

This is important for several reasons—not least is the reputed $36 billion in preferred Fannie stock alone that was ‘taken’ by the government when it claimed Fannie and Freddie were in danger of collapse, and so had to be recapitalized with government support to the tune of $186 billion.

But that has been paid back in spades, and the GSEs are not being allowed to recapitalize. This is when commercial banks that were granted some $350 billion in TARP funds by the same Republican Treasury Secretary under GW Bush (Henry Paulson, former Chairman of Goldman Sachs) were allowed to be recapitalized. So Wall Street benefited, but not Main Street homeowners that for the most part still depend on Fannie and Freddie to guarantee most home loans.

Instead, due to a last minute (2012) ‘tweak’ to the original conservatorship order, all profits go into the Treasury’s General Fund, which has raised suspicions that Treasury is behind the move to capture all profits for its own uses, rather than returning value to preferred stockholders, at least. How is that fair when the GSEs weren’t responsible for the bubble, or subprime loans, or the Great Recession, at all?

We know this because some $14 billion in settlements have already been recovered from those commercial banks and Wall Street entities that submitted fraudulently underwritten mortgages misrepresenting their loan quality to Fannie and Freddie.

The request, made by Fairholme Funds, is a big win for them in the battle to review federally sealed documents in its case against the United States government. Fairholme is one of several former investors in the government-sponsored enterprises who say their ownership stake was illegally taken from them by the federal government during conservatorship. They are fighting in court to get that stake returned.

The more than ten thousand discovery documents will be available to the United States District Court of Appeals in Washington D.C. and the United States District Court.

There is plenty of evidence that Fannie and Freddie were still solvent at the time. Even Treasury Secretary Henry Paulson reassured Congress of their solvency, while Bear Stearns was going under in 2007.

"Fannie Mae and Freddie Mac play an important role in our housing markets today and need to continue to play an important role in the future," Secretary Treasury Henry Paulson told the House Financial Services Committee at a hearing on financial regulation. "Their regulator has made clear that they are adequately capitalized."

And mortgage delinquency rates are almost back to historical levels. For instance, June’s existing-home sales report showed just 8 percent of sales were comprised of forecloses homes, lowest since 2007 and the housing bust.

 image

Graph: Seeking Alpha

The profits have been enormous for US Treasury. “Taxpayers have been paid back and the companies are now left with little capital due to the net worth sweep,” says Seeking Alpha in its latest article on the issue. “Based on Judge Lamberth's ruling (of last year dismissing Fairholmes suit), the government could be sued for a taking if the companies are liquidated. Reform must include adequate compensation to shareholders, as well as a method to bring capital back onto the balance sheet. After 2010, solvency was never a problem.”

And now we have Judge Sweeney ruling in favor of discovery that will enable investors to untangle the ‘rest of the story’.

Harlan Green © 2015

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Wednesday, July 22, 2015

Existing-Home Sales at 8-Year High

The Mortgage Corner

It had to happen.  Why did June existing-home sales jump to an 8-year high? Fewer foreclosures is the short answer, hence more available for sale at market prices. But soaring consumer optimism due to an even better jobs market has to be the driving force causing families to build their nests.

Also, prices are rising to multi-year highs due to supply scarcities. And then there are the demographics, as the new generation is pushing older generations to move up or down, with even baby boomers wanting more retirement living.

Total existing-home sales, which are completed transactions that include single-family homes, townhomes, condominiums and co-ops, increased 3.2 percent to a seasonally adjusted annual rate of 5.49 million in June from a downwardly revised 5.32 million in May. Sales are now at their highest pace since February 2007 (5.79 million), have increased year-over-year for nine consecutive months and are 9.6 percent above a year ago (5.01 million).

image

Graph: Calculated Risk

Lawrence Yun, NAR chief economist, says backed by June's solid gain in closings, this year's spring buying season has been the strongest since the downturn. "Buyers have come back in force, leading to the strongest past two months in sales since early 2007," he said. "This wave of demand is being fueled by a year-plus of steady job growth and an improving economy that's giving more households the financial wherewithal and incentive to buy."

Inventories have dropped to 5 months, which is driving up prices. The median price, up 3.3 percent in the month to $236,400, is already a record. Part of the rise in prices is tied to a lack of distressed sales, at only 8 percent of June's total which is a record low, according to Econoday.

Adds Yun, "June sales were also likely propelled by the spring's initial phase of rising mortgage rates, which usually prods some prospective buyers to buy now rather than wait until later when borrowing costs could be higher."

And that may be an additional factor. Interest rates, though still low, have risen approximately ¼ percent since their most recent lows, with 30-year fixed conforming rates now 3.75 percent for a 1 point origination fee in California.

Total housing inventory3 at the end of June inched 0.9 percent to 2.30 million existing homes available for sale, and is 0.4 percent higher than a year ago (2.29 million). Unsold inventory is at a 5.0-month supply at the current sales pace, down from 5.1 months in May.

"Limited inventory amidst strong demand continues to push home prices higher, leading to declining affordability for prospective buyers," said Yun. "Local officials in recent years have rightly authorized permits for new apartment construction, but more needs to be done for condominiums and single-family homes."

The percent share of first-time buyers fell to 30 percent in June from 32 percent in May, but remained at or above 30 percent for the fourth consecutive month. A year ago, first-time buyers represented 28 percent of all buyers.

This is why housing starts surged nearly 10 percent last month to an annual rate of 1.17 million, just a touch below a post- recession high. Builders were especially active in the Northeast and South that suffered so much from last winter. We need more housing, in other words, as jobs and families continue to grow.

Harlan Green © 2015

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Saturday, July 18, 2015

Housing Starts, Builder Optimism at Recovery Highs

The Mortgage Corner

Privately-owned housing starts in June were at a seasonally adjusted annual rate of 1,174,000. This is 9.8 percent above the revised May estimate of 1,069,000 and is 26.6 percent above the June 2014 rate of 927,000. This tells us the real estate recovery is beginning to contribute to economic growth as it has in past recoveries.

So-called housing starts surged nearly 10 percent last month to an annual rate of 1.17 million, just a touch below a post- recession high. Builders were especially active in the Northeast and South that suffered so much from last winter.

And single-family housing starts in June were at a rate of 685,000; this is 0.9 percent below the revised May figure of 691,000. The June rate for units in buildings with five units or more was 476,000.

image

Graph: Calculated Risk

“While builders are reporting overall confidence in the housing market, they continue to note difficulties accessing land and labor,” said NAHB Chief Economist David Crowe. “These headwinds appear to be affecting production gains in the single-family sector.”

Builder confidence was also the highest since 2005, according to the National Association of Home Builders. Builder confidence in the market for newly built, single-family homes in July hit a level of 60 on the just released National Association of Home Builders/Wells Fargo Housing Market Index (HMI) while the June reading was revised upward one point to 60 as well. The last time the HMI reached this level was in November 2005.

“This month’s reading is in line with recent data showing stronger sales in both the new and existing home markets as well as continued job growth,” said NAHB Chief Economist David Crowe. “However, builders still face a number of challenges, including shortages of lots and labor.”

Construction on multi-dwelling projects with five units or more soared to the highest level since 1987. Builders have devoted more effort to these kinds of projects instead of their traditional focus on single-family homes because of a growing trend toward renting, especially among younger millennials, children of the baby boomers. Greater difficulty in obtaining mortgages has also compelled some people to rent.

Yet rising demand for rental units has also forced up the cost of housing, especially amid a shortage of new units available. A separate government report on Friday showed another sizable increase in the cost of shelter in June, with housing expenses up 3 percent in the past year.

It all points to rising demand for shelter for the millennial generation that is seeing better jobs and has to begin to pay off their huge educational loans. It’s a negative sum game for both student-borrowers and the economy. According to the Consumer Financial Protection Bureau, student loan debt has reached a new milestone, crossing the $1.2 trillion mark — $1 trillion of that in federal student loan debt, says Forbes Magazine.

According to The Institute for College Access and Success (TICAS) Project on Student Debt, the average borrower will graduate $26,600 in the red.  While there are lots of stories of graduates with crippling debt of $100,000 or more, this is the case for only about 1 percent of graduates.  Yet 10 percent of college graduates accumulate more than $40,000.

That is the reason so many millennials can only afford to rent at the moment, and why rental housing construction will be the priority for builders, at least until 2020 when most of the so-called echo boomers (now aged 16 to 35) have matured into adults and begin to form their own families.

Harlan Green © 2015

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Tuesday, July 7, 2015

Pending Home Sales, Mortgage Applications Soar

The Mortgage Corner

Pending home sales continued to rise in May and are now at their highest level in over nine years, according to the National Association of Realtors. Gains in the Northeast and West were offset by small decreases in the Midwest and South. This is why we expect both existing and new-home sales to be the best since 2006 at the height of the housing bubble.

And mortgage activity is soaring, thanks to ultra-low interest rates, with total mortgage origination balances reaching $466 billion in the first quarter -- nearly a 75 percent increase from the same time a year ago, according to the Equifax National Consumer Credit Trends Report.

The Pending Home Sales Index, a forward-looking indicator based on contract signings, climbed 0.9 percent to 112.6 in May and is now 10.4 percent above May 2014. The index has now increased year-over-year for nine consecutive months and is at its highest level since April 2006.

image

Graph: Econoday

Pending sales were strongest in the West, up 2.2 percent in May for a 13.0 percent year-on-year gain. Pending sales in the South, up 10.6 percent year-on-year, have also been strong though the region though lower by 0.8 percent in the latest month. The Midwest was down 0.6 percent for a year-on-year plus 7.8 percent, but were up sharply in the Northeast where housing came back strongly from the severe winter, up 6.3 percent in this report for a year-on-year again of 10.6 percent.

NAR chief economist Lawrence Yun says contract activity rose again in May for the fifth straight month, increasing the likelihood that home sales are off to their best year since the downturn. "The steady pace of solid job creation seen now for over a year has given the housing market a boost this spring," said Yun. "It's very encouraging to now see a broad based recovery with all four major regions showing solid gains from a year ago and new home sales also coming alive."

Equifax said the bulk of mortgage growth has been to first mortgages, which zoomed nearly 80 percent compared to the first quarter of 2014 to $430 billion. The number of first mortgages originated in the first three months of the year was 1.78 million -- a 55 percent increase over the same time a year ago and 14 percent higher than in the fourth quarter of 2014. Originations of home equity lines of credit (HELOCs) rose 30 percent to $30.9 billion and new home equity installment loans climbed 13.6 percent to $5.0 billion.

  • Average first-lien mortgage loan amounts rose to $232,547 in March, an 11.5% increase over March 2014;
  • The number of first mortgages originated in the first three months of the year was 1.78 million, a 54.9% increase over the same time a year ago and 13.6% higher than in the fourth quarter of 2014;
  • The share of first mortgage accounts originated in the first quarter that went to consumers with an Equifax Risk Score below 620 (generally considered subprime) was 4.5%;
  • 3.1% of newly originated balances in the first quarter went to borrowers with subprime credit scores. For the same time a year ago, the share was 3.5%; and
  • The average loan amount for a first mortgage originated to a borrower with a subprime credit score in March 2015 was $152,260, up 9.9% from March 2014.

"The drop in mortgage rates that began in the fourth quarter of last year kicked off a refinance boomlet that accelerated in the first quarter, as rates fell further, averaging just 3.7 percent for the first three months of this year," said Amy Crews Cutts, Chief Economist at Equifax. "While rates have recently reversed that trend and are back up to about 4 percent, they remain extremely low historically. These rates, coupled with a housing market that is showing signs of vigor, should carry the mortgage business over the summer."

So we are seeing the housing sector back to normal growth. Existing-home sales also rose 5.1 percent in May to a 5.35 million annual rate. Home sales were plus 9.2 percent which, outside of the March 11.9 percent, is the strongest rate in nearly two years. And prices are rising, up 7.9 percent year-on-year at a median $228,700.

But, "Housing affordability remains a pressing issue with home-price growth increasing around four times the pace of wages," adds Yun. "Without meaningful gains in new and existing supply, there's no question the goalpost will move further away for many renters wanting to become homeowners."

Harlan Green © 2015

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Tuesday, June 23, 2015

Housing Beginning to Bloom

The Mortgage Corner

Ultra-low interest rates are finally beginning to pay off.  The housing season is beginning to bloom—for first-time homebuyers, in particular. The National Association of Realtors reports total existing-home sales, which are completed transactions that include single-family homes, townhomes, condominiums and co-ops, rose 5.1 percent to a seasonally adjusted annual rate of 5.35 million in May from an upwardly revised 5.09 million in April, largely because of the surge in first time buyers. Sales have now increased year-over-year for eight consecutive months and are 9.2 percent above a year ago (4.90 million).

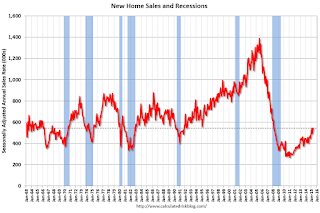
And new-home sales also soared. New single-family homes in the U.S. sold at an annual rate of 546,000 in May, hitting the fastest pace since February 2008, with growth in two of four regions, reports the U.S. Census Bureau this morning. And it revised April's rate to 534,000. May's sales rate was up 19.5 percent from a year earlier, signaling a healthy pick up, though recent sales rates remain below long-term averages.

image

Graph: Calculated Risk

This graph shows existing-home sales, on a Seasonally Adjusted Annual Rate (SAAR) basis since 1993. Sales in May (5.35 million SAAR) were 5.1 percent higher than last month, and were 9.2 percent above the May 2014 rate.

Lawrence Yun, NAR chief economist, says May home sales rebounded strongly following April's decline and are now at their highest pace since November 2009 (5.44 million). "Solid sales gains were seen throughout the country in May as more homeowners listed their home for sale and therefore provided greater choices for buyers," he said. "However, overall supply still remains tight, homes are selling fast and price growth in many markets continues to teeter at or near double-digit appreciation. Without solid gains in new home construction, prices will likely stay elevated — even with higher mortgage rates above 4 percent."

The percent share of first-time buyers rose to 32 percent in May, up from 30 percent in April and matching the highest share since September 2012. A year ago, first-time buyers represented 27 percent of all buyers.

"The return of first-time buyers in May is an encouraging sign and is the result of multiple factors, including strong job gains among young adults, less expensive mortgage insurance and lenders offering low down payment programs," said Yun. "More first-time buyers are expected to enter the market in coming months, but the overall share climbing higher will depend on how fast rates and prices rise."

The huge jump in existing-home sales means more demand for new homes, as we said last week. The median price of new homes fell 1 percent to $282,800 compared with May 2014, also a good sign for the first-time homebuyers. But there are still not enough homes for sale. The supply of new homes was 4.5 months at May's sales pace, down from 4.6 months in April.

New Home Sales

Graph: Calculated Risk

This is also why housing starts came in at a 1.036 million rate in May. Though down 11.1 percent from the April rate, which was already one for the record books. But April is now revised higher to 1.165 million, a 22.1 percent gain from March. Sealing matters is another gigantic surge in permits, up 11.8 percent to 1.275 million following a 9.8 percent gain in April.

And this is buttressed by builder confidence in the market for newly built, single-family homes in June up five points to a level of 59, according to the National Association of Home Builders/Wells Fargo Housing Market Index (HMI). This is the highest reading since September 2014, and in fact returns the index to pre-bubble (2001-02) levels.

Why the huge construction increase in June? This is while mortgage rates are rising, up some 0.375 percent since their most recent lows to 3.875 percent for 0 points in origination fees for a 30-year fixed rate conforming loan.

Firstly, it means consumers are confident enough in their future to begin to look for housing to support their growing families.  And the millennial generation aged 18 to 36 years has already surpassed their parents’ baby boomer population size, and will exceed it by 2020, according to demographers. This has to be why household formation is finally returning to normal levels of 1 million plus new households being formed per year, as the so-called echo boomers move out of their parents’ homes and or leave college to make their own nests.

So forecasters will probably be revising their second-quarter GDP estimates higher following the better housing numbers, not to mention their estimates for Thursday's index of leading economic indicators where permits are one of the components, as we said last week.

Harlan Green © 2015

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Wednesday, June 17, 2015

Housing Construction Soars

The Mortgage Corner

Housing construction is taking off, as I predicted two weeks ago. The numbers show actual construction starts accelerating as well as building permits for future construction. It is also boosting builder confidence to a level that signals continued growth in new construction.

As Econoday reported, “Don't let the headline fool you (i.e., slight drop in June), the housing starts & permits report points to solid strength for the housing sector.” Though the Calculated Risk graph shows how far the housing market is from a true recovery. It is only now returning to the lows of the 1990 recession.

image

Graph: Calculated Risk

Housing starts came in at a 1.036 million rate in May, down 11.1 percent from the April rate but the April rate, which was already one for the record books, is now revised higher to 1.165 million, a 22.1 percent gain from March. Sealing matters is another gigantic surge in permits, up 11.8 percent to 1.275 million following a 9.8 percent gain in April.

And builder confidence in the market for newly built, single-family homes in June rose five points to a level of 59, according to the National Association of Home Builders/Wells Fargo Housing Market Index (HMI). This is the highest reading since September 2014, and in fact returns the index to pre-bubble (2001-02) levels.

image

Graph: Calculated Risk

“The HMI indices measuring current and future sales expectations are at their highest levels since the last quarter of 2005, indicating a growing optimism among builders that housing will continue to strengthen in the months ahead,” said NAHB Chief Economist David Crowe. “At the same time, builders remain sensitive to consumers’ ability to buy a new home.”

All three HMI components posted healthy gains in June. The component gauging current sales conditions jumped seven points to 65, the index charting sales expectations in the next six months increased six points to 69, and the component measuring buyer traffic rose five points to 44, said the press release.

Why the huge construction increase in June? This is while mortgage rates are rising, up some 0.375 percent since their most recent lows to 3.875 percent for 0 points in origination fees for a 30-year fixed rate conforming loan. Firstly, it means consumers are confident enough in their future to begin to look for housing to support their growing families.

And this is, of course, the millennial generation aged 18 to 36 years that has already surpassed their parents’ baby boomer population size, and will exceed it by 2020, according to demographers.

image

Graph: CNBC

Also, household formation is finally returning to normal levels of 1 million plus new households being formed per year, as the so-called echo boomers move out of their parents’ homes and or leave college to make their own nests.

Household formation has been unusually low over the past seven years, averaging 577,000 new households. Whereas, there are approximately 15 million new households per decade being formed during normal times.

So, "there's a ton of people living in basements," Tommy Lee of Fundstrat Global Advisors said in an interview with CNBC's "Trading Nation." "Two quarters of pretty decent household formation isn't getting everybody out of the basement. I think this means we have multiple years where household formations are well over 1.3 million, 1.4 million."

Forecasters will be revising their second-quarter GDP estimates higher following today's report, says Econoday, not to mention their estimates for Thursday's index of leading economic indicators where permits are one of the components.

Harlan Green © 2015

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Tuesday, June 2, 2015

Pending Home Sales In Record Territory

The Mortgage Corner

Pending home sales hit a 9-year high in April, according to data released last Friday by the National Association of Realtors. This is an early sign that housing construction and sales will come out of their winter hibernation, as consumers begin to spend again.

The NAR’s Pending Home Sales Index rose for the fourth consecutive month in April, increasing 3.4 percent to 112.4 – a 14 percent increase over April 2014 and the largest annual increase since September of 2012. The index is now at its highest level since May of 2006.

image

Graph: Econoday

NAR chief economist Lawrence Yun said that there have been steady gains in contract activity each month this year, indicating strong buyer demand. “Realtors are saying foot traffic remains elevated this spring despite limited – and in some cases severe – inventory shortages in many metro areas,” he said. “Homeowners looking to sell this spring appear to be in the driver’s seat, as there are more buyers competing for a limited number of homes available for sale. As a result, home prices are up and accelerating in many markets.”

That has to be why construction spending is surging, as I predicted last week. Higher pending sales mean increased demand for new homes with too few existing homes available for sale at reasonable prices.

image

Graph: Calculated Risk

The U.S. Census Bureau of the Department of Commerce just announced that construction spending during April 2015 was up at a seasonally adjusted annual rate of $1,006.1 billion, 2.2 percent above the revised March estimate of $984.0 billion, and 4.8 percent above the year ago estimate of $960.3 billion.

Private non-residential spending looks very strong, up 3.1 percent and led by the power and office sectors. Public spending is also strong with a large gain for highways & streets, and a surge in educational building. Though the gain in public spending came entirely from the state and local governments as federal construction spending declined for a second straight month.

And personal incomes are beginning to show some life, which may be the underlying reason consumers are feeling more confident. Personal income increased $59.4 billion, or 0.4 percent in April, according to the Bureau of Economic Analysis, though personal consumption expenditures (PCE) decreased just $2.6 billion, or less than 0.1 percent. But we see spending also increasing with increased consumer confidence in future prospects, according to the confidence surveys.

image

Graph: Econoday

The Conference Board’s Consumer Confidence gauge is rising to pre-recession highs; another reason why both new and existing-home sales have been stronger of late. The consumer confidence report for May came in at 95.4, slightly higher than April. Income expectations are up slightly and buying plans are higher across the board, including for autos, homes, and especially for appliances.

The U. of Michigan’s consumer sentiment report also showed strength, ending May at 90.7 vs the mid-month flash of 88.6. The implied reading for the last two weeks of the month is about 93 which, though down from April's 95.9 and January's peak over 98, is still very solid, according to Econoday.

Harlan Green © 2015

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Tuesday, May 26, 2015

New-Home Sales, Case Shiller Index On the Rise

The Mortgage Corner--II

As if to confirm U.S. housing starts and building permits’ jump to their highest levels in nearly 7-1/2 years, the sales rate of new single-family houses in April 2015 rose even higher at a seasonally adjusted annual rate of 517,000, according to estimates released jointly today by the U.S. Census Bureau and the Department of Housing and Urban Development. “This is 6.8 percent above the revised March rate of 484,000 and is 26.1 percent above the April 2014 estimate of 410,000,” per the Census Bureau.

image

Graph: Calculated Risk

It means home construction is returning to pre-recession levels, as is the demand for more housing, which will spur more housing construction. The sales rate is rising fast enough to drop housing inventories to 4.6 months, at the low end of inventories.

The south was the biggest gainer, with construction up 5.8 percent. Also, the median price rose to $297,300 for a strong 8.3 percent year-on-year gain. So sales have finally reached the long term trend line, which should signal a longer term recovery as buyer’s enthusiasm tends to feed on itself, according to Behavioral Economist and Nobelist Dr. Robert Shiller.

image

Graph: Calculated Risk

As if to confirm the rising enthusiasm of buyers, the S&P Case-Shiller Home Price Index continued its climb to post-recession highs, with San Francisco now up 10.31 percent year over year, Denver and Dallas up 10 percent and 9.3 percent, respectively. Denver and Dallas housing prices have almost doubled since the Great Recession, per the above graph. San Francisco’s prices are just now approaching their bubble high.

“Home prices have enjoyed year-over-year gains for 35 consecutive months,” says David M. Blitzer, Managing Director & Chairman of the Index Committee for S&P Dow Jones Indices. “The pattern of consistent gains is national and seen across all 20 cities covered by the S&P/Case-Shiller Home Price Indices…”

Of course lower interest rates were also a factor, as I’ve said, with housing affordability increasing this year, according to the National Association of Home Builders/Wells Fargo Housing Opportunity Index (HOI).

In all, 66.5 percent of new and existing homes sold between the beginning of January and end of March were affordable to families earning the U.S. median income of $65,800, said the report. “This is up from the 62.8 percent of homes sold that were affordable to median-income earners in the fourth quarter.”

What is another catalyst? Housing formation is recovering, which is largely due to Millennials moving out of their parents’ homes, or higher education venues. Based on unusually low household formation numbers of past several years, "there's a ton of people living in basements," Fundstrat Global Advisors' Tom Lee said in a recent interview with CNBC's "Trading Nation." "Two quarters of pretty decent household formation isn't getting everybody out of the basement. I think this means we have multiple years where household formations are well over 1.3 million, 1.4 million."


Household formation will be the key to future housing growth, as the millenials’ population size has now reached that of the baby boomers, their parents. And many have yet to reach home-buying age. Household formation had dipped as low as 360,000 per annum in recent years, due to the housing bust. So this is yet another sign of a growing pool of homebuyers.

Harlan Green © 2015

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Wednesday, May 13, 2015

2015 Housing Construction Will Surge

The Mortgage Corner

We believe housing construction is about to bloom this spring, due to growing employment. For starters, an additional 45,000 construction jobs were added to nonfarm payrolls in April. This is even though construction spending to date has been flat, according to the Commerce Department. The U.S. Census Bureau of the Department of Commerce announced that construction spending during March 2015 was estimated at a seasonally adjusted annual rate of $966.6 billion, 0.6 percent below the revised February estimate of $972.9 billion. But the March figure is 2.0 percent above the March 2014 estimate of $947.3 billion.

And sales of new single-family houses in March 2015 were at a seasonally adjusted annual rate of 481,000, according to estimates by the U.S. Census Bureau and the Department of Housing and Urban Development, which is slow because of winter weather, but it is still 19.4 percent above last year’s March 2014 estimate of 403,000.

And, housing units authorized by building permits in March were at a seasonally adjusted annual rate of 1,039,000, 5.7 percent below the revised February rate of 1,102,000, but is 2.9 percent above the March 2014 estimate of 1,010,000, signaling more construction ahead. And the single-family component is up 4.4 percent from February, which is double the multi-family component. Single family construction employs many more workers per unit.

This is while overall employment could be returning to pre-recession levels, as we said last week. The U.S. churned out 223,000 new jobs in April, and the unemployment rate slid to 5.4 percent from 5.5 percent, which means the US economy’s deep freeze was temporary. It was a short hibernation, in a word, but we are still not out of the Great Recession woods, as we said last week.

image

Graph: Marketwatch

The Small Business Optimism Index also increased 1.7 points from March to 96.9, reports the NFIB, with the employment component especially strong. Small business does 50 percent of all hiring, so this is another sign of a healthy jobs market. Twenty-seven percent of all owners reported job openings they could not fill in the current period, up 3 points from March. And a net 11 percent plan to create new jobs, up 1 point and a solid reading.

image

Graph: Calculated Risk

Lastly, the Labor Department’s most recent JOLTS report showed 5 million job openings, and a higher Quits rate, meaning more workers were able to quit their current job to find a better position. Quits are up 14 percent year-over-year. These are voluntary separations, as we said (see light blue columns at bottom of graph for trend for "quits"), and the number of job openings are up 19 percent YoY, which is another sign of a robust jobs market.

The bottom line is housing construction should begin to expand in the spring and summer. This will ultimately relieve the problem of lack of inventory, and should help first time homebuyers by relieving price pressures that have been increasing as housing stocks have declined.

Harlan Green © 2015

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Tuesday, April 21, 2015

Fannie Says Better Growth For Rest of 2015

Popular Economics Weekly

“Economic activity was suppressed in the first quarter due largely to the West Coast port disruptions and difficult weather patterns across the Northeast, but the economy is expected to gain momentum throughout the spring and reach previously anticipated levels by year-end,” said a just released Fannie Mae’s Economic & Strategic Research Group report.

Is this a repeat of 2014, when growth surged for the rest of the year? It is what happened in 2014, due to last year’s deep freeze. In fact, it should be a repeat, as consumers aren’t spending much in Q1, the weather is as bad—whether blizzard, flood, or drought in the west—and Congress may be as gridlocked in ideological warfare as ever, and is therefore unable to do more harm to growth that it has in the past.

image

Graph: Trading Economics

We started out 2014 with a negative GDP growth rate of minus -2.1 percent. But it jumped to 4.6 and 5 percent in Q2 and Q3, such was the pent up demand from those very good jobs numbers. Just in the last 12 months 3.1 million jobs have been created, and consumers are in an almost ebullient mood. But consumers have to stop saving so much of their increased earnings, if that is to happen.

Fannie believes there’s also another ingredient to boost growth. An improved housing market as incomes improve and interest rates stay near record lows. “Our forecast calls for an increase in economic growth to 2.9 percent for 2015, which is a slight downward adjustment from our prior forecast but solid improvement nonetheless,” said Fannie Mae Chief Economist Doug Duncan

.image

Graph: Econoday

Stronger retail sales gave an indication of the future. Sales of goods and services in March rebounded 0.9 percent after dropping 0.5 percent in February. The market consensus for March was for a 1.1 percent boost. Excluding autos, sales gained 0.4 percent, following no change in February. Expectations were for a 0.6 percent increase. Gasoline sales dipped 0.6 percent after a 2.3 percent increase in February. Excluding both autos and gasoline, sales rebounded 0.5 percent after declining 0.3 percent in February.

 image

Graph: Econoday

However, the Conference Board’s Index of Leading Indicators is not so optimistic about future growth. Its 12 components predicted slower growth over the next 6 months. “In the negative column are building permits which, Thursday's disappointing housing starts report, fell sharply,” said Econoday.” This is a reminder that housing, despite some hopeful signs, has yet to boost economic growth. And declines in the factory workweek and for factory orders are reminders that the manufacturing sector, due in part to weak exports (and strong dollar), may now be pulling down economic growth.”

Let’s hope Fannie Mae is right. “Although we are beginning this year at a more modest pace compared to the above-trend numbers seen at mid-year 2014,” says the report, “the country’s aggregate income has benefitted from the improving labor market, which, combined with low gasoline prices, should help drive higher auto sales and overall consumer spending throughout 2015.”

So it may just be the gloom of winter’s cold that has been holding back economic growth in Q1, especially housing, and that more buyers will enter the housing market this selling season.

Harlan Green © 2015

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Saturday, March 28, 2015

New Home Sales Surging

The Mortgage Corner

New U.S. homes sold at an annual rate of 539,000 in February to mark the best month of sales in seven years, the government reported Tuesday. The pace of sales for January was also revised up sharply to 500,000. It's the first time annualized sales have hit 500,000 or more for two straight months since early 2008.

image

Graph: Calculated Risk

“This is 7.8 percent above the revised January rate of 500,000 and is 24.8 percent above the February 2014 estimate of 432,000," said the Census Bureau. And it reduced the for sale inventory to a 4.7 month supply, which is low considering the pent up demand for housing sales sure to grow this year, with low inflation and rising employment.

Low inflation should be a factor in housing sales this year, if oil prices stabilize, since it boosts householders’ take home pay. Price rises moderated last year. The Federal Housing Finance Authority just reported that same-home prices of homes with conforming loans rose 5.1 percent in January, down slightly from 5.4 percent in December. But we are in mid-winter, so look for more price rises as the spring selling season kicks in.

image

Graph: Econoday

Overall CPI inflation was unchanged in February, which is better than the negative -0.1 percent drop in January. Oil prices have stabilized around $50/barrel for Brent Crude at the moment, but who knows what this year will bring with so much unrest with major oil producers in the Middle East, and even Russia?

image

Graph: Trading Economics

CNBC’s Diana Olick reports that lack of existing-home inventory is the real problem. “Lack of supply of existing homes is pushing prices again, up 7.5 percent year over year to a median sale price of $202,600 in February, according to the NAR, that reported slower February existing home sales,” she says. “And don’t blame it on the weather, according to NAR chief economist Lawrence Yun.

“He calls this reacceleration of price gains, "unhealthy," per Olick. “Affordability had been helping the housing recovery inch along, but now it is weakening and fast becoming a roadblock to homeownership. Still-rising rents are contributing to the problem, keeping first-time buyers from being able to save for a down payment.”

Total existing-home sales, which are completed transactions that include single-family homes, townhomes, condominiums and co-ops, rose 1.2 percent to a seasonally adjusted annual rate of 4.88 million in February from 4.82 million in January. Sales are 4.7 percent higher than a year ago and above year-over-year totals for the fifth consecutive month.

Lawrence Yun, NAR chief economist, says although February sales showed modest improvement, there’s been some stagnation in the market in recent months. “Insufficient supply appears to be hampering prospective buyers in several areas of the country and is hiking prices to near unsuitable levels,” he said. “Stronger price growth is a boon for homeowners looking to build additional equity, but it continues to be an obstacle for current buyers looking to close before rates rise.”

The median existing-home price for all housing types in February was $202,600, which is 7.5 percent above February 2014. This marks the 36th consecutive month of year-over-year price gains and the largest since last February (8.8 percent).

Hence those rising prices and low inventories should spur more new-home construction this year.  But housing construction is barely in recovery mode, and has a long way to go to approach the 800,000 to 1 million unit per year average of past decades.

Harlan Green © 2015

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Monday, March 16, 2015

2014 Household Formation Rebounds

Financial FAQs

Breaking news. The latest Homeownership & Vacancy Survey, released by the Census Bureau, estimated household formation surged to 1.7 million in 2014 from 400,000 the previous year. That is really big news. Household formation, which is the bottom line demand factor for RE sales, mortgage financing, as well as the insurance and construction industries—in fact, anything related to the housing market--may finally begin to show growth from the horrible post-Great Recession years.

image

Graph: Trading Economics

This graph tells the story. Projections were for a recovery to 800,000 new households in 2014, but it looks like Millennials are beginning to leave home, or even college, and form new households in greater numbers—especially the oldest ages from 30 to 36 years. And most demographers agree millennials were born between 1980 to 1996, which means the oldest are reaching the age when they want to start a family, and that usually means buying a home.

Many of those have been renting, and we actually saw a 2.1 million surge in rental units in 2014, which has to account for many of those new households, according to the Census Bureau survey.

In fact, over the past year all the growth in net household formations has been among renters, according to the U.S. Census. For those 35 years old and younger, their home ownership rate has fallen from 44 percent to 36 percent over the past decade, which is why construction of multi-family apartments is at the highest level in a quarter-century this year.

And we know why. They can’t afford to buy until they reach an older age—in fact 30 years of age is when they achieve the median income wage of $42,000, according to a new Georgetown University study.

Through analyzing about three decades of census data—from 1980 to 2012—the study found that on average, young workers are now 30 years old when they first earn a median-wage income of about $42,000, a marker of financial independence, up from 26 years old in 1980.

image

Graph: fivethirtyeight.com

Economists now estimate millennials will spend some $1.6 trillion on home purchases and $600 billion on rent over the next five years, more per person than any other generation with more of them opting for more affordable rents versus paying the big price tags to buy homes, according to a new report from The Demand Institute, a non-profit think tank operated by The Conference Board and Nielsen. Millennials will form just over eight million new households, albeit most of them rental households, as we said.

But there is some good income news. The 2014 numbers aren’t in for a breakdown in median incomes, but the Q4 2014 Federal Reserve Flow of Funds report says the net worth of households and nonprofits rose to $82.9 trillion during the fourth quarter of 2014. The value of directly and indirectly held corporate equities increased $742 billion and the value of real estate rose $356 billion.

This can only boost the millennial generation’s financial well-being, as well, and so the housing market and its ancillary industries.

Harlan Green © 2015

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Monday, March 2, 2015

Pending Home Sales, Consumer Confidence Looking Better

The Mortgage Corner

Oh, the winter is freezing consumers, as I’ve said! It affected January existing-home sales, but the NAR’s January Pending Home Sales index rose sharply 1.7 percent. So pending sales of contracts signed may give a boost to existing-home sales in coming months that fell slightly in January.

Part of the reason for slightly lower home sales, according to the NAR, is that homeowners aren’t changing homes every 7 years on average as they used to. It’s now 10 years, probably due to the busted housing bubble, loss of so much housing equity, and the Great Recession, of course.

image

Graph: Econoday

But this marks the fifth consecutive month of year-over-year gains for pending sales with each month accelerating the previous month's gain, said the NAR.

Lawrence Yun, NAR chief economist, says for the most part buyers in January were able to overcome tight supply which highlights the underlying demand that exists in today's market. “Contract activity is convincingly up compared to a year ago despite comparable inventory levels,” he said. “The difference this year is the positive factors supporting stronger sales, such as slightly improving credit conditions, more jobs and slower price growth.”

“All indications point to modest sales gains as we head into the spring buying season,” says Yun. “However, the pace will greatly depend on how much upward pressure the impact of low inventory will have on home prices. Appreciation anywhere near double-digits isn't healthy or sustainable in the current economic environment.”

He is right, of course. With consumer confidence is at an all-time, post-recession high, which also bodes well for housing demand—though February's consumer confidence index fell 7.4 points to 96.4 from a revised 103.8 in January which was a 7-1/2 year high.

The dip was centered in the expectations component which fell a very steep 9.8 points to 87.2. Could it just be the winter blahs, when jobs are harder to find in part because winter weather keeps consumers from spending more?

image

The second main component of the confidence index, consumers’ present situation, also dipped but less severely, down 2.7 points to 110.2. Here, a closely watched sub-component, jobs currently hard to get, rose 1.6 percentage points to 26.2 percent which is mild indication of weakness for the monthly employment report that comes out this Friday, let us not forget.

The employment consensus is for 230,000 (Wrightson ICAP) to 235,000 (Bloomberg) jobs, a decline in the unemployment rate to 5.6 percent (reversing last month’s surprise uptick), a 0.2 percent increase in average hourly earnings and an unchanged 34.6-hour workweek.

February unemployment reports tend to start out slow and be revised in coming months, as it has in past years—by as much as 50,000 additional jobs, which would boost consumers’ attitudes.

Reuter’s Wrightson ICAP Research says February nonfarm payrolls have been revised over the subsequent two reports in each of the past five years by an average of more than 50K. Their forecast assumes that February nonfarm payroll growth this year will end up somewhere around 280K, so the preliminary estimate probably won’t be quite as strong as the final value. (Their forecast also assumes that the net revision to December and January this month will be positive but probably 25K or less).

Harlan Green © 2015

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen

Thursday, February 26, 2015

January Existing Home Sales, Mortgage Applications Dip

The Mortgage Corner

Oh, the winter freeze! It seems to put the housing market into a deep freeze, as well. Total existing-home sales, completed transactions that include single-family homes, townhomes, condominiums and co-ops, fell 4.9 percent to a seasonally adjusted annual rate of 4.82 million in January (lowest since last April at 4.75 million) from an upwardly-revised 5.07 million in December, said the NAR. Despite January’s decline, sales are higher by 3.2 percent than a year ago.

Lawrence Yun, NAR chief economist, says the housing market got off to a somewhat disappointing start to begin the year with January closings down throughout the country. “January housing data can be volatile because of seasonal influences, but low housing supply and the ongoing rise in home prices above the pace of inflation appeared to slow sales despite interest rates remaining near historic lows,” he said. “Realtors® are reporting that low rates are attracting potential buyers, but the lack of new and affordable listings is leading some to delay decisions.”

image

Graph: Calculated Risk

Better news was that the Chicago Fed National Activity Index (CFNAI) edged up to +0.13 in January from –0.07 in December, with industrial production up. Three of the four broad categories of indicators that make up the index increased from December, and only one of the four categories made a negative contribution to the index in January.

The index is a weighted average of 85 indicators of national economic activity drawn from four broad categories of data: 1) production and income; 2) employment, unemployment, and hours; 3) personal consumption and housing; and 4) sales, orders, and inventories.

Total existing-home inventory at the end of January increased 0.5 percent to 1.87 million existing homes available for sale, but is 0.5 percent lower than a year ago (1.88 million). Unsold inventory is at a 4.7-month supply at the current sales pace – up from 4.4 months in December. The median existing-home price for all housing types in January was $199,600, which is 6.2 percent above January 2014. This marks the 35th consecutive month of year-over-year price gains.

image

This follows the Conference Board’s LEI, which slowed to a not-so-strong plus 0.2 percent versus a slightly downward revised plus 0.4 percent in December. Once again the yield spread is the biggest positive for the index reflecting the Fed's near zero rate policy. Consumer expectations are the 2nd largest positive in the month, though one that may reverse in the next report given last week's plunge in the consumer sentiment index. Credit indications, which continue to be very positive in this report, are the 3rd largest positive.

Both indexes show increased employment in 2015, which should mean home sales will pick up with the selling season and better weather in the spring. “Although sales cooled in January, home prices continued solid year-over-year growth,” adds Yun. “The labor market and economy are markedly improved compared to a year ago, which supports stronger buyer demand. The big test for housing will be the impact on affordability once rates rise.”

Real estate is showing more signs of life, with the Case-Shiller Home Price Index rising again. Data released for December 2014 shows a slight uptick in home prices across the country. The S&P/Case-Shiller U.S. National Home Price Index, which covers all nine U.S. census divisions, recorded a 4.6 percent annual gain in December 2014 versus 4.7 percent in November.

image

Graph: Calculated Risk

Nine cities reported monthly increases in prices ... Both the 10-City and 20-City Composites saw year-over-year increases in December compared to November. The 10-City Composite gained 4.3 percent year-over-year, up from 4.2 percent in November. The 20-City Composite gained 4.5 percent year-over-year, compared to a 4.3 percent increase in November.

image

Graph: US Census Bureau

And lastly, January new-home sales were unchanged, but prices rose. Sales of new single-family houses in January 2015 were at a seasonally adjusted annual rate of 481,000, which is not enough product to keep prices in the affordable range. This is 0.2 percent below the revised December rate of 482,000, but is 5.3 percent above the January 2014 estimate of 457,000.

“In a promising sign, new home sales have been trending at post-recession highs for the past two months,” said NAHB Chief Economist David Crowe. “As the economy strengthens and mortgage rates remain low, we can expect continued upward movement in the housing market this year.”

So still record low interest rates (i.e., 3.50 percent conforming fixed rates) are keeping homebuyer and refinancers interested, but not enthusiastic.   And we believe mortgage rates will remain low, as evidenced by Fed Chairwoman Janet Yellen’s latest congressional testimony, which hinted that said rates could remain low for much of this year.

Harlan Green © 2015

Follow Harlan Green on Twitter: https://twitter.com/HarlanGreen